For years, many homeowners remain on the same home loan without reviewing it. As a result, some may unknowingly be paying a higher interest rate than necessary, while others may not realize that their mortgage protection is outdated or insufficient.
A proper loan review can help uncover valuable opportunities, such as reducing interest costs, lowering monthly repayments, accessing cash-out options, or identifying gaps in existing protection.
In Malaysia, many homeowners only review their home loan when purchasing a property, but rarely revisit it even when interest rates or financial circumstances change.
Even a small difference in interest rate can result in significant savings over a long loan tenure.
What Is a Home Loan Check in Malaysia?
A home loan check involves reviewing key details such as outstanding balance, current interest rate, monthly instalment, loan tenure, and mortgage insurance protection. This assessment helps determine whether refinancing or restructuring your loan makes financial sense and whether there are opportunities to improve your overall repayment strategy.
5 Things a Home Loan Review Can Help You Check
- Interest Savings
Refinancing at a lower interest rate may help reduce total interest paid over time.
- Full-Flexi Flexibility
If you plan to make lump-sum payments, consider switching to a full-flexi loan structure offered by some banks. It will give you the freedom to pay extra anytime, the ability to withdraw excess funds anytime for savings, investments, or any emergencies.
- Lower Instalment
Some step-based loan structures may allow lower instalments in the early years. The reduction in your monthly instalment improves cash flow, giving you more control over it, whether to deposit extra money anytime or withdraw it when needed.
- Cash Out & Debt Consolidation
Cash-out refinancing allows homeowners to take on a larger loan based on their property value and use the excess funds for other financial needs, such as paying off high-interest debts or consolidating multiple loans.
- Mortgage Protection Review
Reviewing whether your current mortgage protection is still suitable or has become outdated or too expensive is an important step in ensuring your property remains fully protected. To ensure your property is fully protected, review the MRTA/ MRTT bundled in the loan.
How Refinancing a Home Loan Can Save Interest
Home loan refinancing means replacing your current home loan with a new one that has better terms, either from the same bank or a different lender.
You might be wondering why refinancing is necessary.
When you want to reduce the interest rate on your home loan to pay less interest, lower the monthly instalment and adjust the speed at which you repay over the loan tenure.
Imagine, based on an RM500,000 loan over 25 years, if your current loan interest is 4.5% from Bank A, but later Bank B says, “I can offer you a cheaper deal of 3.7%,” you could save on your monthly repayment over time.
For example:
- Original total repayment: RM333,748
- After refinancing: RM267,121
- Total interest saved: RM66,627
Disclaimer: Actual savings may vary depending on individual eligibility and are subject to bank approval.
Can Refinancing Help Lower Your Monthly Instalment?
Extending your loan tenure or choosing certain loan structures can help reduce your monthly installments, improving short-term cash flow. However, homeowners should also consider the long-term cost implications before making a decision.
For example, some step-based loan structures may reduce monthly payments by up to 30%, offering significantly lower installments during the early years, especially within the first five years, making it easier to manage your finances in the short term.
When Should You Consider Refinancing Your Home Loan?
You may consider refinancing if:
- Interest rates in the market are lower than your current loan rate
- Your financial situation has improved (e.g., higher income or better credit profile)
- You want to reduce your monthly instalment for better cash flow
- You need to access cash for renovation, debt consolidation, or other purposes
- Your current mortgage protection is outdated or no longer suitable
In these situations, reviewing your loan can help you make a more informed financial decision instead of staying on an outdated loan structure.
Can You Unlock Cash from Your Property Through Refinancing?
Understanding your property equity—the difference between your home’s current market value and the amount you still owe on your mortgage—is key to making informed financial decisions.
Cash-out refinancing may be an option for purposes such as home renovation, debt consolidation, business funding, or education expenses. However, eligibility depends on factors such as property valuation, margin of finance, and overall bank approval.
Why You Should Review Your MRTA or Mortgage Protection
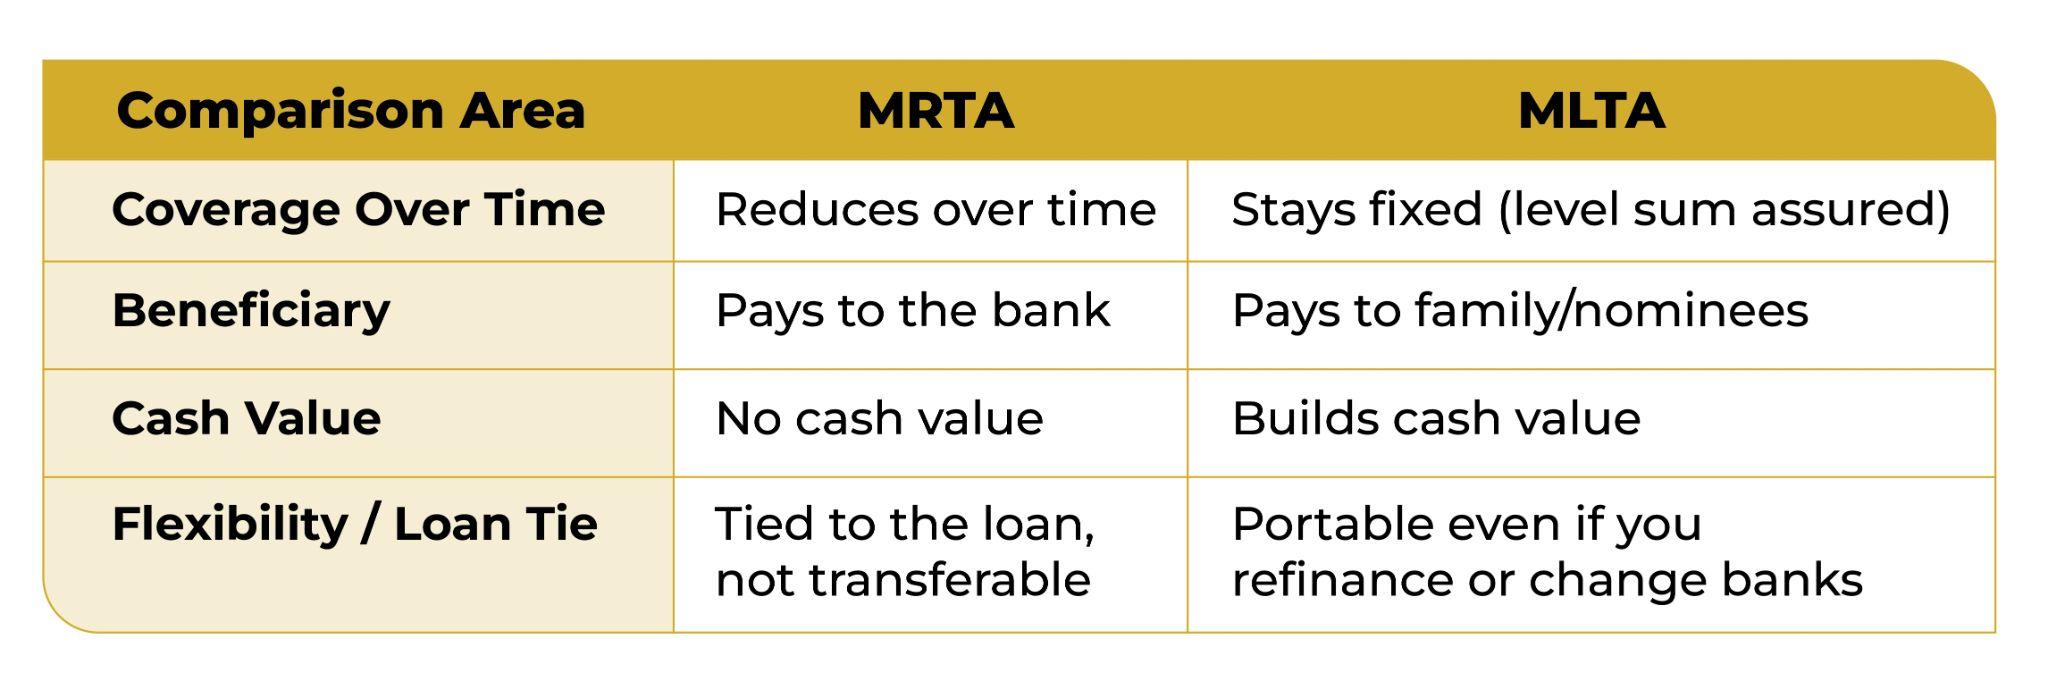
Many homeowners purchased MRTA years ago and have not reviewed their coverage since. Over time, some policies may reduce in coverage, while others expire before the end of the home loan term. They may benefit from reassessing their protection needs and comparing MRTA with MLTA to decide which option better suits their current financial situation.
MRTA vs MLTA – What’s the Difference?
What Information Do You Need Before a Home Loan Review?
Before starting a home loan review, it helps to prepare a few key details about your loan, property, and existing mortgage protection.
Your Current Home Loan Details
You can usually find these details by logging into your bank app or contacting your bank directly:
- Outstanding loan amount
- Current interest rate
- Monthly instalment
- Remaining loan tenure (months/years)
Your Property Information
To access your property’s current value and whether refinancing or cash-out options are available, you will need the following information:
- Property type (e.g. condo, terrace, landed)
- Estimated market value
- Property size and location
- Any major renovations done
Your Mortgage Protection (MRTA/ MRTT) Details
Many homeowners are not aware that their coverage may reduce over time or even expire before their home loan is fully repaid.
- Type of coverage (MRTA/ MRTT, or life insurance)
- Coverage amount
- Coverage term
- Premium paid
- Policy cash value (if any)
What Happens After the Review?
The entire process below can typically be completed within 2 to 4 weeks, depending on the individual’s circumstances and bank approval timelines.
- Review your current home loan details.
- Obtain a tailored proposal based on your financial situation.
- The CSK advisory team will assist you in completing the necessary paperwork.
Key Takeaway
Refinancing is not immediately necessary for every homeowner, but reviewing your current home loan can help you identify potential savings or gaps in your financial protection.
If you’re unsure whether your current home loan is still suitable, starting with a simple review of your loan details can be a practical first step. Understanding your options early can help you make better financial decisions in the long run.